
Blogs
PW Consulting: Detonator Market to Hit USD 12,029M by 2032 at 3.42% CAGR
By pmarketresearch, 2026-07-30
Detonator Market — 2026 Strategic Outlook (PW Consulting)
As companies make capital allocation and portfolio decisions for 2026, clarity about where the detonator market is headed is non‑negotiable. PW Consulting’s Detonator Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes validated market sizing, technology trajectories, and supplier economics into a decision-grade roadmap. The global market has expanded from roughly USD 7.9 billion in 2020 to about USD 9.6 billion in 2025 and — at a compounded annual growth rate of 3.42% across our forecast horizon — is projected to approach the low‑teens billion USD range by 2032. Market structure is moderately concentrated: the top three players collectively hold roughly 30% of value, and the top five about 40% — a dynamic that shapes competitive strategy and partnership calculus.
Detonator Market
Why this study matters for 2026 decisions
-
Timing: 2026 is the inflexion point for product and manufacturing investments. Several leading suppliers completed capacity and automation investments in 2024–2025; entrants and incumbents must decide whether to follow, differentiate, or consolidate.
Detonator Market -
Capital deployment: Firms that wait for perfect certainty will pay a premium in lost share or higher unit costs when demand re‑accelerates. Our analysis turns uncertain signals into explicit investment thresholds and staging plans.
Detonator Market -
Regulatory and customer pull: Lead‑free and precision electronic initiation systems are moving from niche to mainstream in regulated markets. Certification and standards compliance have become tactical gating items for market access.
-
Supply resilience: Recent on‑shoring and regional plant builds underscore supply chain fragility — the right manufacturing footprint choices will materially affect lead times and risk exposure.
What the report delivers — practical, executable content
-
Decision‑grade market sizing and trend diagnostics covering 2020–2032, with baseline, upside, and downside scenarios that embed commodity, regulation, and construction/mining cycle sensitivities.
-
Go‑to‑market playbooks for incumbents and new entrants: channel strategies, service bundling, pricing frameworks, and tender playbooks tailored to mining, industrial, and defense end users.
-
Technology and product roadmaps: actionable recommendations for electronic initiation, lead‑free chemistries, and high‑reliability detonators for aerospace/defense segments, including qualification roadmaps and cost‑to‑serve models.
-
Supply chain and manufacturing diagnostics: factory automation ROI models, localization scenarios, renewable energy integration options, and a supplier risk heatmap to prioritize mitigation actions.
-
Competitive benchmarking and M&A playbook: profiles of strategic peers, capability gaps, acquisition screening criteria, and an integration checklist that preserves regulatory compliance and HSE performance.
-
Procurement and cost engineering templates: unit economics for detonator types, labour and materials sensitivity analyses, and contract structures to balance margin and volume risk.
-
Regulatory impact assessment and ESG roadmap: scenario planning for increasingly stringent environmental standards and defense/aerospace qualification requirements.
High‑level macro takeaways (what senior leaders must internalize)
-
Measured but persistent growth. The market’s expansion from about USD 7.9 billion in 2020 to USD 9.6 billion in 2025, and our projection into the 2032 timeframe, reflects steady demand linked to mining activity, construction cycles, and defense qualification windows. The 3.42% CAGR masks uneven pockets of faster adoption where precision initiation systems and lead‑free solutions have found higher willingness‑to‑pay.
-
Technological bifurcation. Electronic and programmable initiation systems are differentiating on safety, timing precision, and data integration (blast analytics). Parallel advances in lead‑free initiation chemistries are creating regulatory and commercial pull — early movers capture premium pricing in regulated jurisdictions.
-
Manufacturing modernization is a competitive lever. Case examples from recent years show firms investing in fully automated plants and renewable energy at detonator facilities to reduce operating expense and decouple from energy‑price volatility. These investments shorten lead times and lower total cost of ownership for large buyers.
-
Supply chain topology matters. Regional plant openings and on‑shore capacity demonstrate an industry move toward mitigating logistics, compliance, and geopolitical risk. Buyers are increasingly demanding local content and faster replenishment cycles, altering procurement dynamics.
-
Concentration creates transactional and partnership opportunities. With the top three to five firms holding a meaningful but not overwhelming share of value, there is room for targeted consolidation, bolt‑on acquisitions, and strategic alliances — especially where specialized electronic or defense‑qualified capabilities are scarce.
Competitive landscape — strategic reads on leading players
-
Dyno Nobel: Continuing investments in factory automation and energy resilience mark Dyno Nobel as an operator focused on scale efficiency and sustainability. Their portfolio emphasis on electronic initiation systems and automated plants positions them to serve large, safety‑conscious mining clients.
-
Orica Limited: Orica’s push on lead‑free electronic systems and formal certifications reflects a product differentiation strategy aligned with regulatory markets. Their certification milestones reduce adoption friction in Europe and other regulated geographies.
-
Austin Powder Company: With offerings spanning electronic, electric, and non‑electric systems, Austin Powder combines product breadth with industrial blasting services — a useful model for mixed‑portfolio operators seeking relational contracts with mines and civil contractors.
-
MAXAM and Enaex: Both firms illustrate regional strength coupled with focused electronic solutions. Enaex’s programmable detonators and MAXAM’s electronic lines show the increasing value of precision timing in blast optimization services.
-
Specialty suppliers (Chemring, Excelitas, Teledyne): These players secure high‑value, technically demanding pockets — defense, aerospace, and specialized industrial clients — where qualification standards and traceability requirements create higher barriers to entry.
-
Regional manufacturers and new capacity (BME Mining Canada, Kırlıoğlu, Nelson Brothers, Ideal Mining Services): Recent plant openings and local production capabilities highlight an industry pivot to mitigate supply chain risks and meet regional content expectations.
Recent industry moves to watch (2024–2026)
-
Automation and energy initiatives: Several major manufacturers completed or expanded automated electronic detonator plants and renewable energy installations at detonator/booster sites, reducing operating cost volatility and improving sustainability credentials.
-
Regional capacity builds: New plant openings in established mining jurisdictions reflect a strategic push to de‑risk logistics and shorten lead times for critical initiation products.
-
Product certification and lead‑free adoption: Market leaders secured certifications that enable the commercial rollout of fully lead‑free electronic detonators across regulated markets, unlocking procurement pipelines in Europe and beyond.
Strategic imperatives for 2026
-
Prioritise capability bets: Decide whether to invest in in‑house electronic initiation, buy capabilities through M&A, or secure long‑term supply agreements. The right choice depends on scale, end‑market mix, and regulatory exposure.
-
Localize selectively: Use a triage of lead time, regulatory risk, and customer demand to determine where regional manufacturing is justified versus where centralized, low‑cost production remains optimal.
-
Accelerate qualification programs: For players targeting defense, aerospace, or highly regulated mining markets, front‑loading qualification (and certification) shortens commercial ramp timelines and creates durable differentiation.
-
Embed digital value: Electronic detonators that provide timing data and blast analytics can be monetized through service contracts and analytics subscriptions — turn a component sale into a recurring revenue stream.
-
Mitigate raw‑material and labour risks: Scenario plans should quantify exposure to specialized labour shortages and shifts in explosive feedstock; hedges and dual‑sourcing arrangements are no longer optional.
-
Use M&A to fill capability gaps: In a market with moderate concentration, bolt‑ons can provide rapid access to electronic know‑how, regional footprint, or defense qualifications without the time and compliance burden of greenfield builds.
How PW Consulting supports your 2026 agenda
-
Bespoke strategy workshops that convert the global forecast and supplier benchmarking into an executable 12–36 month roadmap.
-
Investment‑grade financial models and scenario simulators, calibrated to your cost base and optionality points (manufacturing, qualifications, product R&D).
-
M&A origination and diligence support: targeted screening, regulatory pathway mapping, and integration playbooks that preserve HSE and certification continuity.
-
Procurement transformation: supplier scorecards, contract playbooks, and negotiation templates designed to secure resilient supply at predictable unit economics.
For senior leaders preparing 2026 capital and commercial plans, the choice is clear: act on high‑confidence signals now or accept the strategic drag of catching up later. PW Consulting’s Detonator Market report provides the data, scenarios, and playbooks to make those decisions with conviction. The executive summary above highlights core insights and practical implications; the full report contains the detailed segment tables, regional demand matrices, and supplier scorecards that underpin these recommendations. Access the complete intelligence package to move from strategic intent to execution-ready plans.
For detailed analysis of this topic, please visit the official page: Detonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Amorphous Metal Cores Market Set to Grow at 7.5% CAGR Through 2032
By pmarketresearch, 2026-07-30
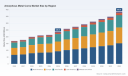
Amorphous Metal Cores Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, forward-looking primer on the amorphous metal cores market designed to inform executive decisions in 2026. This article synthesizes the market’s macro trajectory, competitive dynamics, and the strategic levers that will matter most to manufacturers, utilities, investors, and policy makers over the next strategic planning cycle. The intent is to demonstrate analytical depth while preserving the granular segmentation and proprietary datasets for the full report—viewing this as a high-value “preview” that signals where to dig deeper.
Amorphous Metal Cores Market
Market trajectory at a glance
The amorphous metal cores market has shifted from a niche technical solution to a measurable industrial market. On a consolidated basis (USD, revenue in Million), the market rose from roughly 169.5 in 2020 to about 236.5 in 2025, and is projected to reach approximately 385.6 by 2032, representing a compound annual growth rate of 7.5% over the forecast window. The immediate forecast point for 2026 sits near 259.2, underscoring continued near-term momentum.
Amorphous Metal Cores Market
These macro figures reflect a combination of demand-side drivers—grid modernization, stricter energy-efficiency regulations, and growth in distributed power electronics—and supply-side responses including capacity investments and material innovation. For executives planning 2026 capital allocation, these topline dynamics frame the probability of demand growth and the expected cadence of returns on investments tied to amorphous core production and integration.
Amorphous Metal Cores Market
Why this matters for 2026 corporate decisions
-
Capital allocation and capacity planning: A sustained mid-single-digit to high-single-digit CAGR implies that greenfield capacity or targeted expansions can achieve utilization thresholds within typical payback horizons—provided deployments are matched by offtake agreements and cost optimization.
-
Product portfolio and R&D prioritization: The technology landscape is bifurcating between cores optimized for lowest no-load loss in distribution transformers and alloys tailored to high-frequency power electronics. Prioritizing R&D to either improve core material performance or lower processed ribbon/unit costs will be a differentiator.
-
Procurement and supplier strategy: Supply-chain localization and strategic supplier partnerships (including tolling or licensing arrangements) will be important to manage raw-material volatility and geopolitical risk. Early contractual choices in 2026 will determine cost curves for the next five years.
-
M&A and alliance playbooks: With a moderately concentrated supply base (CR3 and CR5 metrics indicating industry concentration in the high-20s to low-30s percent range), targeted acquisitions or JVs can be used to secure technology, capacity, or market access without necessitating broad-scale consolidation.
Key strategic themes shaping the market
-
Energy-efficiency arbitrage: Regulatory tightening and utility-level TCO assessments place a premium on transformer cores that materially reduce no-load losses. Leading material technologies can lower no-load loss substantially versus conventional electromagnetic steel, changing replacement economics for utilities and industrial end-users.
-
Electrification and power-electronics demand: The accelerating deployment of EV infrastructure, renewables, and data-center power systems lifts demand for both low-frequency distribution cores and high-frequency specialized core materials. Product roadmaps should accommodate both waveforms and thermal profiles.
-
Localization of production: Manufacturers are rebalancing footprints toward end-market proximity to reduce logistics, currency exposure, and tariffs. Recent capacity moves indicate a strategic bet on local demand capture and faster time-to-market.
-
Material and process innovation: Alloy composition and strip processing (ribbon casting, annealing, coating) remain the technologic frontier. Some grades now claim materially higher saturation flux density and targeted performance across frequency ranges—attributes that alter component-level trade-offs.
-
Scale economics vs. customization: The industry will reward firms that can marry large-volume, low-cost ribbon production with nimble downstream core-forming and value-added assembly for specialized applications.
Competitive landscape — what executives need to know
The market’s competitive structure combines global technology leaders with regional or vertically integrated producers. A few strategic observations:
-
Proterial, Ltd. / Metglas, Inc. — Operating as primary producers of Metglas™ amorphous ribbon, these businesses combine proprietary alloy know-how with multi-continent production footprints. Notably, the group is expanding capacity with a new production site in India slated to come online in late 2026, a move that signals an intent to secure domestic demand and improve regional cost positions. Their commercial claims—such as a roughly one-third reduction in no-load loss compared to traditional electromagnetic steel in select transformer applications—are central to their product value proposition.
-
VACUUMSCHMELZE (VAC) — VAC’s VITROVAC® family demonstrates the industry’s material differentiation strategy. With Fe-based grades offering high saturation flux density (reported up to ~1.74 T for select alloys), VAC positions itself for applications requiring both power density and performance at frequency extremes.
-
Chinese volume players — Several large Asian manufacturers have scaled ribbon and core production, combining cost-competitive volume output with service models tailored to domestic and export customers. Their strategic advantage lies in manufacturing scale, integration with transformer OEMs, and supply-response agility.
-
Specialist manufacturers — Niche players that focus on particular core geometries or downstream assembly remain attractive partners for OEMs seeking tailored solutions, rapid prototyping, or bundled supply arrangements.
Collectively, the market exhibits moderate concentration (CR3 and CR5 metrics point to a sector where the top players control meaningful—but not dominant—share). This structure fosters both competitive pressure on pricing and opportunities for well-targeted vertical or geographic moves by challengers.
What the full PW Consulting report delivers
The companion market study provides the complete analytical toolkit executives need to act in 2026. Highlights include:
-
Comprehensive historical time series (2020–2025) and a transparent forecast model (2026–2032) with scenario sensitivity to material cost, regulatory shifts, and demand shocks.
-
Granular segmentation by product type, application, and geography (including downloadable tables and pivot-ready datasets). Note: this preview intentionally omits the detailed split tables to preserve proprietary insights available in the full report.
-
Supplier scorecards and SWOTs for the principal manufacturers, including capacity maps, technology differentiators, and recent capex announcements.
-
Demand-driver dossiers—regulatory lineage, utility procurement frameworks, and end-market adoption curves—translated into procurement and product-development decision rules.
-
Commercial playbooks: go-to-market strategies, partner-screening templates, sample offtake and tolling contract terms, and negotiation levers to secure long-term advantage.
-
Investor-ready financial models and IRR/NPV scenarios for greenfield production, brownfield expansion, and technology licensing cases.
-
Practical checklists for manufacturing transition (ribbon sourcing, annealing line investments, quality control metrics, and recycling loops).
How to use these insights in 2026
-
C-suite: Use the topline CAGR and forecast horizon to set capital allocation thresholds—define minimum utilization targets for new capacity and prioritize investments that shorten time-to-revenue (e.g., capacity in-market, strategic partnerships).
-
Product leaders: Align R&D roadmaps with the two-track demand profile—low-loss distribution transformer cores and materials optimized for higher-frequency inverters and converters. Focus on thermal management and manufacturability alongside magnetic performance.
-
Procurement heads: Reassess supply arrangements through a geography-and-risk lens. Evaluate short-term purchase agreements with options that scale into long-term contracts tied to indexed pricing or pass-through mechanisms to manage raw-material swings.
-
Investors and PE: Screen targets using the report’s supplier scorecards and valuation scenarios. The current concentration metrics indicate room for bolt-on acquisitions that can rapidly expand addressable capacity without creating monopoly risk.
Methodology note and limitations
The analysis is grounded in a transparent framework: historical base year 2025, historical series 2020–2025, and forecasts for 2026–2032. Revenue is reported in USD (Million) and growth is presented on a nominal basis with a central CAGR of 7.5% for the forecast interval. Company intelligence combines public filings, official product literature, press releases (including recent capacity announcements), and primary interviews. As a preview, this article omits detailed segmentation tables and certain unitized regional or application-level figures—those are available in the full dataset.
Next steps
For executives preparing budgets, negotiating supplier agreements, or evaluating strategic transactions in 2026, the full PW Consulting Amorphous Metal Cores Market report delivers the quantitative slices and negotiation-ready playbooks you need. The preview above highlights where value can be captured and where risk is concentrated—but the precise levers (regional mixes, application-specific adoption curves, and supplier-by-supplier capacity schedules) are contained in the complete study. Access the full report to download the forecast model, supplier scorecards, and the contract templates that we use with clients to translate insight into action.
PW Consulting stands ready to brief leadership teams, run tailored scenario workshops, and model bespoke investment cases. If your 2026 planning cycle depends on getting material, capacity, or product choices right, treat this market as a strategic lever rather than a technical accessory.
For detailed analysis of this topic, please visit the official page: Amorphous Metal Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Ferulic Acid Market to Reach USD 90.22 Million by 2032 at 6.7% CAGR
By pmarketresearch, 2026-07-30
Natural Ferulic Acid (CAS 1135-24-6): Strategic Preview for 2026 Decision‑Makers
Executive snapshot
Natural ferulic acid has moved from a niche specialty ingredient to a commercially relevant natural actives category with clear implications for sourcing, formulation and regulatory positioning. Our latest market study (base year 2025) models a steady expansion from a global market sized in the mid‑tens of millions of USD in 2025 to a near‑nine‑figure opportunity by the end of the 2026–2032 forecast window at an implied compound annual growth rate of 6.7%. For 2026 corporate planning, this is not a marginal trend—it's a multi‑year demand trajectory that should inform procurement, R&D prioritization and go‑to‑market strategies across cosmetics, nutraceuticals and specialty food applications.
Natural Ferulic Acid (CAS 1135-24-6) Market
Why this research matters in 2026
- Actionable horizon: The report translates a medium‑term CAGR into discrete strategic options—sourcing hedges, product roadmaps and M&A triggers—that are executable within 12–24 months.
- Risk‑calibrated guidance: We combine market sizing with supply‑chain sensitivity analysis so executives can translate growth expectations into contract structures that protect margins against agricultural feedstock variability.
- Regulatory & positioning playbook: As clean‑label and “naturally sourced” claims gain regulatory scrutiny across core markets, the study outlines compliance pathways and labeling strategies that preserve premium positioning without introducing litigation risk.
Market trajectory and what the numbers imply
The market’s projected growth profile—a consistent mid‑single‑digit CAGR—reflects a balance of demand expansion in higher‑value applications (cosmetics and nutraceuticals) and ongoing supply constraints tied to natural extraction. In practical terms, companies planning capacity, budgets or product launches in 2026 should assume a tightening supply environment relative to demand growth, which will put a premium on long‑term supplier relationships, vertically integrated sourcing, or alternative feedstock strategies.
Natural Ferulic Acid (CAS 1135-24-6) Market
Our modeling shows a clear inflection: incremental demand is strong enough to reward early movers who secure diversified raw materials and who can convert supply reliability into preferred supplier status with OEMs and formulators. For investors, the growth trajectory supports disciplined capital deployment into extraction capacity, formulation platforms, and bolt‑on targets that deliver immediate route‑to‑market synergies.
Natural Ferulic Acid (CAS 1135-24-6) Market
Supply‑side dynamics: raw material dependency and cost volatility
Natural ferulic acid is primarily extracted from agricultural byproducts—most notably rice and wheat brans. That biologically anchored supply base creates two structural realities. First, production costs and yield are seasonal and tied to crop cycles; second, geographic concentration of processing capacity matters because logistics and feedstock proximity materially affect delivered cost and lead time.
- Price risk: Agri‑feedstock volatility can propagate quickly through extraction margins. Fixed‑price contracts and index‑linked purchasing are both viable mitigants; the optimal choice depends on a firm’s risk tolerance and balance‑sheet flexibility.
- Feedstock diversification: Procuring from multiple cereal sources and investing in extraction process flexibility reduces single‑source risk and creates negotiating leverage.
- Technical differentiation: Extraction efficiency and downstream purification quality are critical differentiators. Players with improved yield or lower impurity profiles command a valuation premium in B2B negotiations.
Demand dynamics and regulatory tailwinds
Demand is being driven by two converging forces: formulators seeking natural antioxidant and UV‑stabilizing actives, and consumer preferences shifting toward clean‑label, naturally derived ingredients. Regulatory regimes in major markets increasingly favor transparency about ingredient origin, which benefits genuinely natural suppliers but increases validation and documentation requirements.
- Cosmetics and nutraceuticals lead: High‑value formulations that credibly leverage natural sourcing and scientifically backed claims create the fastest margin expansion opportunities.
- Compliance costs: Expect higher compliance and certification costs for suppliers that wish to claim “natural” across multiple jurisdictions—companies must budget for traceability systems, third‑party validation and extended product dossiers.
- Private‑label and brand risk: Brands that use low‑cost synthetic alternatives may face consumer scrutiny; as a result, many mid‑to‑premium brands will pay a premium for documented natural sourcing.
Competitive landscape — what incumbents reveal about strategic options
The competitive field is characterized by a mix of long‑standing specialists, regional champions and vertically integrated vegetable oil/bran processors. That mix produces a market that is neither a pure commodity race to the bottom nor a closed oligopoly—there is room for differentiation based on feedstock, purity, formulation support and customer intimacy.
- Zhejiang Delekang Food Co., Ltd. (China) — A veteran producer focused on rice bran extraction with a track record of cost‑competitive supply for food and cosmetics customers. Their scale and commodity know‑how make them an attractive partner for volume buyers seeking competitive pricing.
- TSUNO Group Co., Ltd. (Japan) — Notable for patented high‑dosage UV‑absorbing formulations and ongoing product development. Recent 2026 activity includes exhibition at major trade shows and new consumer launches leveraging domestically sourced rice‑bran ferulic acid, signaling an integrated approach from feedstock to finished consumer format.
- Okayasu Shoten, Oryza Oil & Fat Chemical, HSF Biotechnology, Shaanxi Guanjie, Hubei Yuancheng and Xi'an App Chem — These firms collectively illustrate the spectrum of capabilities: advanced extraction efficiency, high‑purity manufacturing, feedstock specialization (wheat vs rice bran) and targeted application expertise (pharma vs cosmetics). Each represents a different strategic partner archetype—cost leader, technical innovator, or regulatory‑compliant supplier.
For buyers and investors, the takeaways are clear: leverage supplier archetypes to match strategic needs (scale vs. purity vs. development support), and expect that top domestic specialists and regional champions will continue to shape pricing and availability in their home markets.
Strategic playbook for 2026 — five immediate actions
- Lock strategic offtake where price/volume terms align with scenario planning. Prioritize multi‑year agreements with flex windows tied to feedstock indices to balance risk and cost predictability.
- Invest in feedstock diversification and dual‑sourcing. Even small additional sourcing options materially reduce exposure to seasonal shortages or regional crop failures.
- Accelerate formulation partnerships that turn natural ferulic acid from an ingredient into a differentiating consumer claim. Co‑developed formulations reduce time‑to‑market and create switching costs for customers.
- Build regulatory dossiers and traceability. For premium positioning, expect to invest in third‑party certifications and digital traceability—these are now table stakes in key markets.
- Evaluate targeted M&A or JV activity in 2026–2027. With the market growth profile, small bolt‑ons that expand feedstock access, purification capability or application expertise can generate rapid strategic payback.
Scenario considerations (practical and quick to model)
Use three short scenarios when stress‑testing capacity or pricing decisions: a baseline aligned with the mid‑single‑digit CAGR, an upside driven by accelerated cosmetic & nutraceutical adoption, and a downside driven by raw‑material shocks or regulatory friction. The levers that most affect outcomes are feedstock price volatility, conversion efficiency and the pace of premium formulation adoption. In our models, these three variables explain the majority of variance in margin outcomes over the next three years.
What the full report delivers (practical contents)
Our study is designed for executives and investment teams who need executable intelligence, not just charts. Highlights include:
- Detailed market sizing and growth drivers (2020–2025 historical, 2026–2032 forecast) with build‑ups that link demand by application to unit economics.
- Supply‑chain maps and supplier profiles with capability matrices and contact‑ready checklists for commercial negotiations.
- Sensitivity and scenario models you can adapt to internal cost structures, including raw‑material elasticity tables and break‑even curves for different contract structures.
- Regulatory and claims matrix for major markets outlining compliance steps to preserve “natural” labeling and minimize downstream litigation risk.
- Commercial playbooks for buyers, formulators and investors—pricing strategies, co‑development templates and M&A decision matrices.
Final perspective and recommended next step
2026 is a decision inflection point for many organizations exposed to natural actives. The growth path for natural ferulic acid is substantial enough to warrant explicit strategy work—procurement hedging, formulation partnerships, and selective capacity investments are now timely. However, converting growth into margin requires deliberate choices about supplier archetypes, feedstock strategy and regulatory positioning.
To move from directional insight to operational decisions, access to the full report is essential: it provides the granular models, supplier contact frameworks and contract language that enable rapid execution. PW Consulting’s full study is structured as a playbook—designed to convert the 6.7% CAGR opportunity into measurable commercial outcomes over the next 18 months.
For teams planning 2026 budgets, product launches or M&A screens, start with a focused review of the supply‑risk chapter and the scenario model that aligns best with your cost structure—then use the supplier profiles and negotiation templates to convert insight into secured access.
For detailed analysis of this topic, please visit the official page: Natural Ferulic Acid (CAS 1135-24-6) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot-Work Die Steels Market to Reach USD 344.8M by 2032 (6.98% CAGR)
By pmarketresearch, 2026-07-30
Hot-Work Die Steels Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
The Hot-Work Die Steels market has moved from a niche durability play into a strategically material segment of advanced tooling supply chains. Measured on a global basis, the market reached USD 215.0 Million in our base year (2025) after recovering from pandemic-era volatility and is projected to expand at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. By 2032 the market is expected to exceed USD 340 Million, driven by demand for higher-duty dies, tighter tolerances in forged and cast components, and rising adoption of alloy and process improvements that extend die life under severe thermal cycling.
Hot-Work Die Steels Market
Why this research matters for 2026 corporate strategy
For manufacturing leaders, die makers and materials buyers, 2026 is shaping up as an inflection year. Policy shifts (including new carbon border adjustments and emissions limits), consolidation among European suppliers, and continued product engineering advances are simultaneously compressing supplier choice and raising the stakes of sourcing and innovation decisions. This research presents the market-level view required to align sourcing, R&D investment, and M&A priorities with near-term constraints and mid-term opportunity.
Hot-Work Die Steels Market
-
Timing: With new tariffs and carbon-related measures taking effect around 2026 in key markets, procurement and localization strategies must be set now to avoid margin erosion.
Hot-Work Die Steels Market -
Technology pivot: Thermal-management improvements and cleaner metallurgy are changing the value equation for die steels — you either play the long-life, premium-die game or compete on lower-cost, higher-replacement models.
-
Consolidation window: Recent and announced integrations (notably the GMH Gruppe integration in early 2026) open both supply-side scale and consolidation arbitrage for strategic buyers and partners.
What the report delivers — practical, executable content
This market study is structured to support immediate 2026 decision cycles. It blends quantitative market sizing and scenario forecasting with operational playbooks that translate insight into actions. Key deliverables include:
-
Robust market sizing and top-line forecasts for 2026–2032 based on sector drivers and sensitivity to raw-material and regulatory scenarios.
-
Supply-chain diagnostics: identification of pinch-points for high-purity alloy inputs (chrome, molybdenum, vanadium), logistics risk maps and alternative sourcing ladders designed for rapid deployment.
-
Regulatory impact modelling that translates EU emissions rules and carbon border adjustments into cost-per-ton and sourcing penalty vectors for different supply origin scenarios.
-
Commercial playbooks: supplier selection scorecards, long-term off-take vs spot procurement decision matrices, and procurement contracting templates oriented to die-life total cost of ownership (TCO).
-
R&D and product strategy guidance: priority areas for alloy chemistry and heat-treatment investments, and a roadmap to deploy thermal-conductive and high-toughness grades for specific die-making use cases.
-
M&A and partnership scenarios: where scale matters (production capacity, ESR/VIM facilities, vacuum hardening expertise) and how to structure deals to unlock synergies quickly.
Market dynamics and near-term catalysts
Several interacting forces will define competitive advantage in 2026 and beyond:
-
Material science advances. Suppliers are launching grades with improved thermal conductivity and high-temperature strength — an example being a new hot-work grade aimed at extending mold service life and reducing operating cost per part.
-
Regulatory pressure. European limits on emissions from electric arc furnaces and the roll-out of carbon border adjustment mechanisms require buyers to quantify embedded carbon and evaluate near-shore or compliant suppliers.
-
Standards-driven quality expectations. ISO specifications governing impact toughness for hot-work die steels impose minimum properties that affect both vendor qualification and warranty exposure.
-
Raw material tightness. Premium hot-work grades require high-purity chrome-molybdenum-vanadium inputs; supply constraints or price shocks in these alloys disproportionately affect specialty steel pricing and availability.
Operationally, the sector is also experiencing a labor- and skills-driven shift: specialized heat-treatment proficiencies, particularly vacuum hardening and ESR processing know-how, have risen in importance (with notable increases in required skilled labor since 2024), altering where and how value is captured in the supply chain.
Competitive landscape — who moves the market
The market remains fragmented: the leading companies together account for roughly a quarter of total market revenue, leaving a long tail of regional and specialty producers. This fragmentation breeds both competition and acquisition opportunity.
-
Japanese leadership in alloy R&D and cleanliness: companies such as Daido Steel, Sanyo Special Steel, Nippon Koshuha, Proterial and several specialty mills continue to push metallurgical boundaries with grades optimized for die casting, forging and extrusion. Their strengths include vacuum metallurgy, high-purity product lines and strong OEM relationships in automotive and industrial equipment.
-
European premium capability and consolidation: suppliers such as voestalpine High Performance Metals, Swiss Steel Group and Aubert & Duval combine advanced processing (ESR, VIM) with engineering services. Swiss Steel’s recent grade launch (late 2025) and the GMH Gruppe integration (completed in January 2026) are examples of how European players are seeking product-led and scale-led differentiation.
-
Regional producers and capacity plays: Asian producers across China and India (including several large-scale steelmakers and specialty mills) provide competitive supply for commodity-lean applications, giving buyers options where carbon and regulatory exposure are manageable or where cost pressure is paramount.
-
North American specialists: boutique tool-steel producers and service-focused companies (e.g., Hudson Tool Steel and Southern Tool Steel) maintain close relationships with die shops and OEMs, offering localized response and aftermarket services that reduce downtime.
For buyers and strategic planners, the implications are clear: metallurgical superiority and low-carbon production credentials command premiums; meanwhile, geographic footprint and service models determine price-to-value in procurement negotiations.
Strategic implications and recommended levers for 2026
Based on our synthesis, executives should execute a coordinated set of actions across four dimensions in 2026:
-
Secure supply and diversify alloy sourcing: establish dual-sourcing for high-purity alloy inputs, and structure long-term contracts that include embedded carbon clauses to address CBAM exposure.
-
Prioritize product and process differentiation: invest in thermal-management and surface engineering to extend die life, and partner with suppliers who offer ESR/VIM capacity and demonstrable low-CO2 footprints.
-
Operationalize locale and compliance: where tariffs or carbon mechanisms bite, consider near-shore production or co-investment in compliant mills to preserve margin and lead times.
-
Use M&A and partnerships tactically: pursue bolt-on acquisitions or JV partnerships to acquire vacuum hardening, ESR capacity or specialty alloy lines rather than broad horizontal deals — the market rewards depth over scale for technical capabilities.
How to use this report in your 2026 planning cycle
We designed the research to be immediately actionable for board-level strategy sessions and operational procurement teams alike. Practical use-cases include:
-
Baseline scenario planning: overlay the report’s market forecast and regulatory impact analysis onto your volume and margin forecasts to derive adjusted capital and working-capital plans.
-
Supplier scorecarding: adopt the report’s supplier evaluation templates to re-run vendor assessments with carbon, metallurgy and service response incorporated.
-
Deal readiness: use the M&A playbooks and synergy schematics to evaluate target mills and to fast-track integration planning where acquisitions are pursued.
-
R&D and CapEx prioritization: align alloy development projects and heat-treatment investments with the report’s timing for premium grade adoption to maximize payback.
Conclusion — the strategic choice for 2026
The hot-work die steels market is neither a low-risk commodity arena nor a purely bespoke boutique sector: it sits at the intersection of high-precision metallurgy, regulatory exposure and operational intensity. For 2026, companies that move early to secure compliant alloy supply, partner on high-performance grades, and rationalize service-oriented offerings will capture outsized value as the market grows at a near 7% CAGR toward 2032.
This preview intentionally highlights trends, competitive dynamics and decision levers while preserving the granular subsegment and regional breakdowns that are core to procurement and investment actions. For the full data tables, segment-level forecasts and supplier scorecards that operational teams require for contract and capital decisions, access the complete report on our site and download the supporting appendices.
For detailed analysis of this topic, please visit the official page: Hot-Work Die Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cell Isolation Market to Grow at 13.62% CAGR Through 2032
By pmarketresearch, 2026-07-30
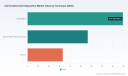
Cell Isolation & Cell Separation Market — Strategic Brief for 2026 Decision-Makers
Executive overview
As cell-based science accelerates from bench research to approved therapies and high-volume biomanufacturing, the cell isolation and separation market is maturing into a strategic infrastructure layer for life-science organizations. PW Consulting’s latest study (base year 2025) frames that transition with a data-driven market trajectory: from an estimated market in 2025 to a long-term forecast through 2032 driven by a compounded annual growth rate of 13.62%. The market’s historical evolution and multi-year forecast together illuminate where near-term investments will compound into sustainable advantage by 2028–2032.
Cell Isolation/Cell Separation Market
Market trajectory at a glance
-
Historical momentum: Our modeling traces a rapid recovery and expansion from the 2020 inflection point through 2025, reflecting increased adoption across research, clinical translation and early commercial cell therapy manufacturing.
Cell Isolation/Cell Separation Market -
Near-term inflection (2026): The market is set to continue its strong growth into 2026 and beyond; our forecast period (2026–2032) quantifies this momentum and scenarios for scale-up across both instruments and consumables.
Cell Isolation/Cell Separation Market -
Market structure: Concentration metrics indicate a market where a handful of global players retain meaningful share but room remains for specialist entrants and regional service providers to capture niche and adjacencies.
Why this report matters for 2026 corporate strategy
-
Investment prioritization — R&D vs. scale: The report identifies which product archetypes (automation platforms, high-throughput sorters, disposable consumables, closed-system processing) generate faster commercial ramp and recurring revenue, enabling finance and R&D leaders to prioritize capital allocation and product roadmaps.
-
M&A and partnership signal-mapping: Consolidation is selective and strategic. The study provides acquisition targets and partnership archetypes that accelerate entry into clinical GMP workflows, high-throughput sorting, or service-delivery models without overpaying for low-margin instrumentation.
-
Go-to-market optimization: With changing reimbursement and regulatory signals, device makers and CMOs must align sales channels, value propositions and pricing policies to both research and clinical buyers. Our analysis translates market growth into addressable opportunity by buyer persona and procurement cycle.
-
Regulatory & reimbursement readiness: The full research frames immediate compliance actions and payer engagement strategies that materially affect commercial timelines for clinical and commercial-scale cell processing.
What’s inside the report — practical outputs for action
-
Robust market sizing & scenarios: Bottom‑up market models (base year 2025) with sensitivity scenarios for conservative, base and accelerated adoption paths through 2032. Each scenario ties directly to key adoption drivers so leaders can stress-test investment choices.
-
Go-to-market playbooks: Tactical GTM templates for vendors and service providers, including channel selection matrices, segmented pricing playbooks, and customer-value messaging tailored for academic labs, biopharma CDMOs, and hospital/diagnostic end users.
-
Technology roadmaps and adoption curves: Comparative timelines for automation, magnetic separation, flow-based sorting and filtration modalities — including recommended trigger points for product launches and upgrade cycles.
-
Operational and manufacturing KPIs: Benchmarks for throughput, yield, cost-per-sample, and cleanroom/GMP conversion paths to guide capital equipment decisions and scale-up investments.
-
Regulatory & reimbursement playbook: Actionable guidance to align product development and submission strategies with evolving payer rules and device pathways, and checklists for GMP transition, ISO 13485 compliance and clinical trial integration.
-
Competitive landscaping and vendor scorecards: Deep, qualitative assessments (strengths, vulnerabilities, product roadmaps) of tier‑1 and emerging vendors with pragmatic partner evaluation criteria for alliances, OEM and distribution agreements.
-
M&A & corporate development toolkit: Valuation comparables, deal archetypes, integration risk checklists and a shortlist of capability gaps that acquisitions or JVs can rapidly fill.
-
Case studies & commercial pilots: Real-world examples illustrating how lab networks, CMOs and instrument vendors moved from pilot projects to recurring revenue models.
Competitive landscape — core players and strategic implications
The market is shaped by a mix of specialized innovators and diversified life‑science conglomerates. The competitive narratives below synthesize each player’s strategic posture and the near-term implications we expect to matter for 2026 planning.
-
STEMCELL Technologies Inc. — A specialist in immunomagnetic kits and automated sorters, STEMCELL’s recent acquisition of high‑throughput sorter technology accelerates its push into automated, high-purity sorting for cell therapy manufacturing. Expect bundled consumable+automation offerings and expanded service/validation support as their priority.
-
Miltenyi Biotec — A leader in clinically oriented magnetic-activated cell sorting and closed-system platforms with strong GMP pedigree. Its platforms are positioned for clinical translation; regulatory endorsements and clinical customer referenceability remain core advantages.
-
Thermo Fisher Scientific — Leverages scale and breadth across reagents, beads and instrument lines to offer end-to-end workflows for bead-based therapies. Their strategic play is integration — from consumables to manufacturing-scale workflows — and competitive pricing at volume.
-
Becton, Dickinson and Company (BD) — With flow cytometry systems and reagent suites, BD targets high-throughput, high-purity sorting for both research and translational labs. BD’s channel reach into hospitals and diagnostic labs is a powerful route-to-market for in-vitro diagnostics adjacent use-cases.
-
Danaher (Cytiva) — Focused on closed, GMP-scale processing and filtration systems, Cytiva is a natural partner for biomanufacturers scaling to commercial cell therapy batches. Its strength is process integration with bioprocessing ecosystems.
-
Merck KGaA (MilliporeSigma) , Agilent , Beckman Coulter , Terumo BCT , Lonza , Bio‑Rad — Each brings pockets of strength: reagent platforms, analytical/sorter combos, apheresis and clinical processing, or GMP-oriented consumables. Strategic partnerships and co-development agreements are the fastest way for niche vendors to scale with these incumbents.
Recent developments and regulatory backdrop
-
Notable transactions and service launches signal an emphasis on automation and outsourced services. For example, the integration of high‑throughput sorting technology into incumbents’ portfolios and the launch of commercial FACS services in regulated markets are early indicators of a shift toward service-enabled revenue models.
-
Regulatory and payer shifts materially affect unit economics. Recent policy changes that integrate certain manufacturing steps into reimbursement calculations and limited device exemptions under humanitarian pathways introduce both opportunities and constraints for commercialization timelines.
-
Quality and device certification remain table stakes. Major platforms adhere to ISO 13485 and other GMP-relevant standards — a requirement for market access in clinical programs and aggregated purchasing by CMOs and hospitals.
-
Emerging designations for manufacturing technologies that reduce process impurities are accelerating adoption in therapeutic manufacturing, and companies that can evidence lower host‑cell DNA or improved safety attributes can capture premium positioning.
Strategic imperatives for 2026
-
Prioritize consumables-led monetization: Consumables drive recurring revenue and create platform lock-in. Product leaders should design upgrade paths that combine single-use kits with subscription inventory models and validation support.
-
Invest selectively in automation that unlocks scale: Automation investments should be prioritized where they demonstrably reduce cost-per-dose, reduce variability, and shorten release cycles — criteria that matter to CDMOs and large biopharma customers.
-
Embed regulatory strategy into product design: Early alignment with GMP, ISO 13485 and payer requirements reduces time-to-market friction. Consider clinical-grade SKU roadmaps and companion validation packages for rapid customer qualification.
-
Build service and lab-network offers: Outsourced processing and commercial FACS services are accelerating. Vendors that can provide validated service networks or asset-light partnerships with third‑party labs will capture a portion of outsourced spend.
-
Use M&A to fill capability gaps: Bolt-on acquisitions in automation, high-throughput sorting, or software for process analytics can compress time-to-market and achieve scale economies faster than organic development.
-
Engage payers and policy makers proactively: Changes to reimbursement treatment for cell-manufacturing steps require proactive engagement to preserve economic models for clinical and commercial therapies.
-
Harden supply chain and manufacturing readiness: Single-use consumables and bespoke reagents require resilient sourcing and predictable manufacturing scale plans to support larger clinical and commercial customers.
Final note — where to go next
PW Consulting’s full Cell Isolation/Cell Separation Market report provides the confidential, segment-level breakdowns, vendor scorecards and model files needed to translate the headline growth trajectory into executable 12–36 month plans. This strategic brief is structured to show the depth of our analysis while preserving the detailed segmentation and financial models that are the operational tools for decisive action. For the full dataset, scenario workbooks and bespoke advisory support to convert this intelligence into a tailored market-entry or scale-up plan, please refer to the PW Consulting report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page: Cell Isolation/Cell Separation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Mode Blue Laser Diode Market Poised for 8.6% CAGR Through 2032
By pmarketresearch, 2026-07-30
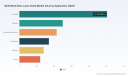
Multi-Mode Blue Laser Diode Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present this preview to frame the strategic choices companies must confront in 2026 as the multi-mode blue laser diode market transitions from niche growth to mainstream industrial relevance. This piece synthesizes our market modeling, competitive analysis, and actionable strategic frameworks — enough to inform board- and C-suite-level discussions while reserving the granular segment-level figures for the full PW Consulting report.
Multi-Mode Blue Laser Diode Market
Executive snapshot
- Market trajectory: The global multi-mode blue laser diode market has expanded from roughly USD 1.85 Million in 2020 to USD 2.80 Million in 2025 (base year). Our forecast projects continued expansion through the 2026–2032 horizon, with the market reaching approximately USD 4.99 Million by 2032.
- Compound growth: A 2026–2032 CAGR of 8.6% underpins this projection and highlights robust adoption across industrial, projection and high-value applications.
- Structure: Market concentration remains moderate — the top three players account for roughly a quarter of the market, with the top five near 30% — implying both established leaders and meaningful room for challengers and niche specialists.
Why this matters for 2026 strategy
2026 is a pivot year. The market has moved beyond early adopters into a phase where suppliers, system integrators, and OEMs must choose how to capture value: deepen technical differentiation, pursue scale through consolidation, or fight for pockets of premium margin in specialized applications. The 8.6% CAGR signals sustained opportunity, but success will depend on aligning go-to-market moves with structural forces — technology maturation (GaN and packaging), thermal and reliability engineering, and the evolving needs of industrial, imaging, and consumer systems.
Multi-Mode Blue Laser Diode Market
Macro dynamics shaping the market
- Technology maturation: Advances in GaN epitaxy, multi-die integration, and packaging have elevated optical outputs and lifetime characteristics. These technical gains expand the addressable application set for multi-mode blue diodes — from projection and display engines to high-precision industrial processing.
- Demand vectors: A convergence of demand from industrial processing, display/projection, medical devices, and automotive sensing is diversifying pull for higher-power multi-mode solutions. The transition from single-purpose to multi-application platforms favors suppliers who can offer modular, thermally-robust, and cost-competitive modules.
- Supply-side constraints: Critical bottlenecks include thermal management at scale, die yield for high-power multi-die assemblies, and packaging supply chains. Companies that secure proprietary packaging, optical coupling IP, or downstream system integration will have a durable advantage.
- Competitive concentration: With CR3 around 25% and CR5 around 30%, the market is neither a tight oligopoly nor a fragmented free-for-all. This structure supports targeted M&A and partnership plays to capture scale without triggering major antitrust concerns in most jurisdictions.
Competitive landscape — strategic implications
The competitive map includes established optoelectronics majors, component specialists, and laser systems companies. Each incumbent brings different strengths that dictate complementary moves for partners and competitors alike.
Multi-Mode Blue Laser Diode Market
- Nichia Corporation (Tokushima, Japan): A technology leader in GaN-based blue laser diodes with strong IP and an emphasis on high-power modules. Strategic implication: Nichia is the partner of choice for firms prioritizing supply stability and proven GaN device performance; challengers must out-innovate on integration, thermal/IP packaging, or system-level differentiation.
- ams‑OSRAM AG (Austria): Recent product launches — notably a high-output Vegalas Power series device introduced in late 2025 — demonstrate a push into projection and display markets with high optical power multi-die designs. Strategic implication: OEMs in projection and imaging should evaluate Vegalas-class devices for short-term performance gains while negotiating supply and co-development terms to lock in roadmaps.
- Sony and Sharp (Japan): Both leverage vertical integration into consumer electronics and display subsystems. Strategic implication: Expect tight coupling between diode roadmaps and system-level designs — companies supplying consumer or display OEMs should prioritize APUs and interface compatibility.
- ROHM and Panasonic (Japan): Emphasize diversified portfolios across medical and automotive domains. Strategic implication: These suppliers are attractive for regulated sectors where compliance, long lifecycle support, and conservative qualification regimes matter.
- Coherent, IPG Photonics, TRUMPF (USA/Germany): These are system-oriented or high-power industrial providers who design modules and turnkey systems around diode arrays. Strategic implication: They are ideal partners for customers seeking plug-and-play industrial solutions; they also represent potential consolidation targets for companies looking to move up the value chain.
Decision-making frameworks for 2026
We recommend executives evaluate strategic options using three interlocking frameworks:
- Value capture matrix (product vs. system): Decide whether to compete at the component level (diode IP, die manufacturing), the module level (thermal/optical packaging, driver electronics), or the system level (turnkey industrial machines, projection engines). Margins and investment scale differ materially across these layers.
- Risk-adjusted investment funnel: Allocate development and M&A capital across low-risk supply security actions (long-term offtake agreements), medium-risk integration bets (packaging and module engineering), and high-risk disruptive plays (novel diode architectures, vertical integration into systems). Use staged gates keyed to yield and MTBF milestones.
- Partner orchestration ladder: Map strategic partners by capability (epitaxy, packaging, thermal solutions, optical subsystems) and design collaborative engagement — from IP licensing to JV manufacturing — that preserves optionality while accelerating time-to-market.
Practical moves for 2026
Based on our scenario modeling and supplier landscape review, here are prioritized actions for executives planning 2026 strategies:
- Secure supply continuity: Negotiate multi-year supply and capacity reservations with primary diode manufacturers, or co-invest in packaging capacity to mitigate lead-time risk.
- Invest in thermal and packaging IP: Small-to-medium investments in thermal interface materials, active cooling control algorithms, and optical coupling reduce system-level costs and increase deployment reliability.
- Pursue selective M&A or strategic alliances: Targets include specialized packaging houses, high-yield epitaxy fabs, and module integrators to rapidly climb the value chain.
- Differentiate on integration: Focus R&D on software-driven beam control, modular optics, and serviceable module designs to lock customers into longer product lifecycles and recurring revenue streams.
- Prepare regulatory and qualification paths: For medical and automotive applications, invest early in compliance testing and long-term reliability programs to accelerate certification timelines.
What the full PW Consulting report delivers (operationally focused)
While this preview sketches strategic contours, the full report is intended as an operational toolkit for 2026 planning cycles. Key practical deliverables include:
- Granular market model with annualized revenue exercises (historical 2020–2025 base and forecasts 2026–2032) and scenario toggles to test adoption rates, price erosion, and supply constraints.
- Detailed segmentation by region, device type, and application with interactive sensitivity analysis (kept out of this preview to preserve research exclusivity).
- Supplier heatmaps and a mapped ecosystem of upstream suppliers, packaging specialists, and system integrators — annotated with capability scores and risk flags.
- Competitive dossiers on leading manufacturers, including technology roadmaps, recent product launches, patent posture, and suggested engagement strategies for each player.
- Operational playbooks: due-diligence checklists for M&A, sample term-sheet language for long-term supply agreements, and an integration timeline calibrated to production ramp profiles.
- Investment case templates and an ROI calculator tailored to common strategic options: module development, manufacturing co-investment, and system-level expansion.
Concluding view — positioning for optionality
The multi-mode blue laser diode market is entering a formative stage where technological improvements, a sustained mid-single-digit to high-single-digit CAGR, and a moderate competitive concentration converge to create differentiated pathways for value capture. 2026 will reward firms that balance near-term supply security with medium-term bets on packaging and system integration. Whether the objective is to lead on component IP, to assemble differentiated modules, or to deliver turnkey systems, the strategic imperatives are clear: secure capacity, invest in integration IP, and align M&A and partnership activity to preserve optionality.
Next steps
PW Consulting’s full Multi-Mode Blue Laser Diode Market report (base year 2025; forecast period 2026–2032) contains the detailed segment analytics, interactive models, and executable playbooks referenced above. For decision-makers preparing budgets, M&A pipelines, or product roadmaps in 2026, this report is structured to convert insight into action. Contact our research team or visit our report page to access the complete intelligence package and the downloadable operational toolset.
For detailed analysis of this topic, please visit the official page: Multi-Mode Blue Laser Diode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Agar Market to Reach USD 432.18 Million by 2032 at 5.0% CAGR
By pmarketresearch, 2026-07-30
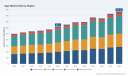
Agar Market 2026 Strategic Primer: What Decision‑Makers Need to Know
Executive summary
As organizations set strategy for 2026, the agar market presents a blend of steady growth, concentrated supplier power, and episodic supply risks that make targeted intelligence indispensable. Our market model, calibrated to a 2025 base year and built on historical observations from 2020–2025, shows a compound annual growth rate of roughly 5% through the 2026–2032 forecast window. That trajectory translates into a clear, investable expansion path over the coming six years, with mid‑single‑digit organic demand growth, punctuated by short runs of volatility in raw material availability and pricing.
Agar Market
For senior executives — commercial leads, procurement chiefs, and corporate development teams — this research functions as a strategic playbook: it reframes the agar market from a commodity mindset to a portfolio of differentiated opportunities (from food & beverage uses to high‑value agarose resins for bioprocessing). Importantly, this introduction is a trailer: it demonstrates analytic depth and line of sight while reserving the granular segment matrices and price curves for the full report.
Agar Market
Why 2026 is a pivot year
-
Growth is steady but selective. The market’s mid‑single‑digit CAGR suggests predictable baseline demand — enough to support new investments, but not so rapid that late entrants will be rewarded without a focused strategy.
Agar Market -
Concentration matters. Market concentration metrics indicate the top three and top five players hold material influence over pricing and standards, making strategic supplier relationships and competitive positioning decisive for margin recovery and share gain.
-
Supply shocks are real and recent. Global raw material movements have led to significant price spikes in discrete periods; these episodes translate directly into margin pressure for manufacturers and higher procurement risk for buyers.
Key dynamics shaping near‑term decisions
-
Raw material supply volatility. The extraction of agar from red algae links the industry to geographically concentrated biological resources and weather patterns. In late 2023, market reports documented a sharp spike in spot prices for agar-agar powder in China, underscoring how limited supply can translate quickly into global cost pressure. For 2026 planning, stress‑tested procurement strategies and multi‑sourcing arrangements should be treated as baseline investments, not optional insurance.
-
Regulatory and quality expectations. Laboratory and clinical applications demand traceability and certified manufacturing. Leading producers supplying clinical and pharmaceutical customers operate under regulated systems and recognized standards; compliance investments (e.g., FDA registration, USP alignment, ISO QMS) materially affect total cost of ownership and time‑to‑market for higher‑value product lines.
-
Trade patterns and logistics. Export leadership is concentrated among a few countries, while certain markets remain reliant on imports. Freight dynamics, trade policy shifts, and regional sourcing preferences continue to shape build vs. buy decisions for end‑users and OEMs alike.
-
Product differentiation is increasingly strategic. Commodity agar still exists, but the most attractive pockets for margin improvement are in specialized agarose resins and application‑tailored grades for cell culture, diagnostics, and chromatography. These subsegments require closer collaboration with end customers and higher technical service intensity.
Competitive landscape — what incumbents are signaling
The market is served by a mix of global laboratory suppliers, specialized producers, and regional manufacturers. The competitive map is characterized by a few large, branded players with broad product portfolios and regulatory footprints, alongside niche specialists that target high‑value bioprocess and chromatography applications.
-
Becton Dickinson (Franklin Lakes, NJ, USA): A legacy supplier of bacteriological media and culture agars, with product lines targeted at diagnostic and microbiology laboratories. Their brand presence and distribution network make them a reference supplier for regulated end markets.
-
MilliporeSigma (Merck KGaA) (Burlington, MA, USA): Supplies agar and agarose grades across cell culture, microbiology, and research applications. Their portfolio and global reach position them as a preferred partner for life‑science customers seeking certified, high‑consistency inputs.
-
HiMedia Laboratories (Global operations headquartered in the U.S. for certain markets): Focused on dehydrated culture media and agars for microbiology and pharmaceutical testing, with regulatory certifications that support clinical and QA/QC end users.
-
Java Biocolloid (Indonesia): A regional specialist emphasizing native and specialty agars (including organic and fast‑soluble formats) for food, pharma, and industrial segments — a reminder that product innovation can be an effective route to commercial differentiation even from smaller bases.
-
Agarose Bead Technologies (ABT) (Burgos, Spain with US operations): A focused manufacturer of agarose resins and chromatography beads, actively investing in capacity and market expansion for bioprocess applications — their recent facility investments and trade‑show commitments indicate clear ambition in the high‑value subsegment.
Company activity across 2025–2026 underscores two themes: incumbents are consolidating their hold on regulated and high‑service markets, while smaller, specialized players are expanding selectively into high‑margin niches. For potential investors or partners, the choice between scale and specialization will determine which partnerships or acquisition targets make sense.
What the full report delivers (practical, decision‑ready content)
PW Consulting’s full agar market study has been structured for immediate operational use, not just high‑level briefing. Highlights include:
-
A forward model (2026–2032) with scenario runs (baseline, downside supply shock, and upside innovation adoption) to stress revenue and margin outcomes under realistic permutations of raw material and regulatory shock.
-
Supplier scorecards and a buyer‑supplier heat map that codify capabilities, regulatory certifications, and strategic fit for different end uses — enabling procurement and quality teams to prioritize vendor engagements.
-
Price‑sensitivity and margin impact tools that translate raw material price moves into P&L outcomes at various points along the value chain, calibrated to observed historical volatility.
-
Go‑to‑market playbooks by application cluster that guide product positioning, required certifications, and sales engagement models — particularly for higher‑value agarose and lab‑grade segments.
-
M&A and partnership screens: prioritized target profiles, valuation heuristics, and integration risk checklists for buyers seeking immediate scale or tech‑led capability additions.
-
Risk and resilience checklists covering sourcing diversification, inventory buffers, contractual clauses (e.g., force majeure and indexation), and contingency logistics pathways.
How to use this research in 2026 — recommended actions
-
For procurement leaders: implement multi‑tier sourcing for critical grades and adopt hedging or indexed contracts for exposure to raw material swings. Run the report’s supply‑shock scenario to quantify required buffer inventory and allowable lead times.
-
For commercial teams: prioritize differentiated product lines (e.g., agarose resins, certified lab agars) where technical barriers and service expectations defend pricing. Align go‑to‑market resources to support technical onboarding in clinical and bioprocess customers.
-
For M&A and corporate development: use the report’s target screen to evaluate bolt‑on buys that accelerate access to specialty resins or regional supply hubs. Pay attention to integration risks tied to regulatory compliance and plant certifications.
-
For R&D and product leaders: invest in formulation and process improvements that reduce raw materials intensity or increase product performance (e.g., faster solubility, organic/clean‑label grades). These innovations can convert commodity buyers into long‑term partners.
-
For risk managers: codify trigger points for activation of contingency plans (price thresholds, supplier failure rates) and test logistics playbooks against a realistic shock event modeled in the study.
Signal versus noise — what this primer leaves intentionally out
This brief intentionally surfaces the strategic implications and the analytical architecture without reproducing the granular segmentation matrices, region/application breakdowns, and proprietary price‑by‑grade curves that underpin our scenario runs. Those elements are the core of the paid study because they materially affect tactical choices (e.g., which regional market to prioritize first, which application pockets justify capex). If you are evaluating deployment of commercial resources, sourcing reorganization, or an acquisition strategy in 2026, access to that granular intelligence will materially de‑risk execution.
Next step
PW Consulting’s full Agar Market 2026–2032 report contains the detailed tables, sensitivity models, and action templates referenced here. For buyers and leaders who must make decisions in 2026 — particularly those weighing supply‑chain resilience, premium product investments, or strategic acquisitions — the complete model and playbooks provide the necessary level of granularity to translate strategic intent into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Agar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Entertainment Systems to hit USD 345.4M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
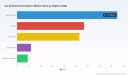
Car Entertainment System Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our latest Car Entertainment System Market study — a strategic briefing designed to shape executive decisions in 2026. The market has entered a new phase: from a recovery and digital-integration cycle in the early 2020s to a sustained expansion driven by software-defined vehicle architectures, immersive in-cabin experiences, and tighter integration between infotainment and safety domains. Using 2025 as the base year, our modeling shows the global market expanding from approximately USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and forecasted to reach USD 345.4 Million by 2032, representing a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 period. This trajectory creates windows of opportunity — and distinct execution risks — that require targeted strategic action in 2026.
Car Entertainment System Market
Why this study matters for 2026 decision-makers
-
Timing of platform bets: The industry is shifting from hardware-led differentiation to software- and services-led differentiation. OEMs and Tier‑1 suppliers who decide on platform architectures and software partnerships in 2026 will lock in multi-year product roadmaps and partner ecosystems.
Car Entertainment System Market -
Monetization inflection: Subscription models, over‑the‑air (OTA) feature rollouts, and aftermarket upgrade pathways are moving from pilot projects to commercial programs. Strategic choices on pricing, feature bundling, and revenue-sharing will materially affect lifetime value.
Car Entertainment System Market -
Certification and regulatory alignment: New certification frameworks for Android Automotive and AAOS-based IVI systems introduce compliance overheads and preferred testing routes—decisions on where and how to validate systems now carry program-level implications.
-
Consolidation and supplier strategy: The market remains relatively fragmented (CR3 ~24.6%; CR5 ~26.2%), creating a dual dynamic — room for niche innovation and an attractive runway for consolidation. Strategic M&A, joint ventures, or exclusive supply agreements could be decisive moves in 2026.
What the full report delivers (actionable, not academic)
-
Proprietary market sizing and forecasting model (base year 2025; historic tail to 2020; forecast 2026–2032) with scenario outputs for high/medium/low adoption pathways, enabling sensitivity analysis for CAPEX and revenue planning.
-
Technology radar that ranks platform approaches (native AAOS vs. proprietary stacks), audio and display innovations (spatial audio, HDR certifications), SoC integration strategies, and connectivity/vehicle domain convergence.
-
Commercial playbooks: OEM vs. aftermarket go‑to‑market templates, pricing and subscription frameworks, partner selection checklists, and go/no-go gates for feature monetization pilots.
-
Operational toolkits: supplier sourcing scorecards, qualification matrix for IC and SoC partners, certification roadmaps (including Android Automotive/AAOS testing), and a compliance impact matrix for procurement and quality teams.
-
M&A and partnership playbook: valuation benchmarks, consolidation scenarios, and integration risk checklists tailored to the current fragmentation levels and competitive dynamics.
-
Risk scenarios and mitigation: supply-chain shocks, software security incidents, regulatory shifts, and consumer-UX adoption hurdles — each with contingency plans and milestones for 12‑ to 36‑month horizons.
Competitive landscape: how to read incumbent moves
Our competitive analysis focuses on strategic positioning, software and ecosystem relationships, product roadmaps, and commercial reach. Below are the key players and the implications of their recent moves.
-
Harman International (Stamford, CT) — Strengths: premium connected systems, immersive audio, integrated UX. Strategic signal: Harman’s industry-first HDR10+ automotive certification (announced late 2025 / reinforced in 2026) is evidence of investment in media-quality differentiation and OEM co-development for premium segments. For partners, Harman represents a platform play for experiential, content-driven monetization.
-
Pioneer Corporation (Tokyo) — Strengths: aftermarket leadership, navigation and audio systems. Strategic signal: Pioneer’s SPHERA (early 2026) — an aftermarket in-dash receiver embedding Dolby Atmos into Apple CarPlay — underscores the aftermarket as a rapid-prototyping ground for advanced audio UX and a channel to capture incremental consumer spend. OEMs should watch aftermarket innovations as demand signals for future OEM features.
-
DENSO TEN Limited (Kobe) — Strengths: AV products and automotive electronics. Strategic signal: DENSO TEN continues to play the classic Tier‑1 role — integrating hardware reliability with evolving software stacks — making it a candidate partner for OEMs prioritizing integration depth and production-grade quality.
-
Panasonic Automotive Systems (Yokohama) — Strengths: in‑vehicle infotainment, navigation, premium audio. Strategic signal: Panasonic’s systems remain attractive to OEM programs that seek end‑to‑end integration across cabin subsystems and premium UX. The firm’s focus on modular IVI platforms supports faster OEM time-to-market.
-
Mitsubishi Electric Automotive America (Northville, MI) — Strengths: connected infotainment, integrated cockpit, rear-seat entertainment. Strategic signal: Mitsubishi Electric is positioned to capture platforms that require heterogeneous cockpit experiences across occupant zones — a growing demand vector as vehicle interiors become multi-purpose spaces.
-
Bosch (Stuttgart) — Strengths: infotainment ECUs, central computing, connectivity. Strategic signal: At CES 2026 Bosch demonstrated a fusion of infotainment and driver assistance on a single SoC-based cockpit & ADAS integration platform. That convergence underscores a strategic tilt toward domain consolidation — a structural shift that will redefine supplier boundaries and integration complexity.
-
Continental AG (Hanover) — Strengths: information management, connectivity solutions. Strategic signal: Continental remains a key systems integrator; its strength in connectivity and data management positions it for roles in vehicle-to-cloud monetization and centralized cockpit services.
Additional market activity (e.g., Fiacre Telematics’ showcase of commercial-vehicle infotainment at mobility expos) evidences niche growth vectors where customized solutions and regional regulatory alignment matter most.
Regulatory and certification dynamics to watch in 2026
-
P3 Group’s role as Google’s third‑party laboratory for Android Automotive testing and the formalization of AAOS certification frameworks creates a de facto gate for many OEMs and suppliers. This reduces technical ambiguity but raises program costs and time-to-certification.
-
Practical implication: product teams must bake AAOS test plans into development sprints, and procurement must select certified test partners early to avoid downstream delays. The report includes an executable certification checklist and vendor selection rubric.
Priority strategic moves for 2026
-
Embed software-first thinking into product roadmaps: Move from one-off feature launches to modular, OTA-enabled platforms with clear update governance and rollback plans.
-
Lock in certification pathways early: Allocate budget and program timelines for AAOS certification and preferred third‑party lab engagements.
-
Define clear monetization experiments: Pilot subscriptions and feature tiers in targeted regions or customer segments; instrument pilots to capture conversion and churn metrics.
-
Prioritize integrations that reduce system complexity: Consider consolidation of cockpit domains where safety‑critical and infotainment workloads converge; evaluate SoC partners with demonstrated multi-domain performance.
-
Build strategic partnerships across the ecosystem: app-platform providers, cloud service vendors, audio content partners, and certified test labs — not just hardware vendors.
-
Use M&A selectively to accelerate capability gaps: With modest top-5 concentration, tuck-in acquisitions or JV structures can quickly secure software talent, content deals, or aftermarket distribution.
-
Invest in cybersecurity and privacy-by-design: With increasing vehicle connectivity, embedded IVI systems are high-value targets; security investments must be part of the product budget, not an afterthought.
How PW Consulting can accelerate your 2026 program
Our full Car Entertainment System Market report is built as an execution guide: downloadable financial models, procurement scorecards, certification roadmaps, a partner‑selection matrix, and scenario-based investment cases tuned to the 2026 decision calendar. The public preview you’re reading now intentionally omits granular segment breakouts and granular regional/application-level revenue tables — those detailed splits and program-level benchmarks are included in the subscriber report to preserve commercial integrity and to give paying clients immediate, prioritized value.
If your 2026 roadmap requires defensible investment cases, faster certification, or a market-entry playbook for OEM and aftermarket channels, the full study provides the templates and advisory engagement options to convert strategic intent into milestones and measurable outcomes.
In short: the Car Entertainment Systems market is growing, recentering around software and experiential differentiation, and is opening strategic windows for firms that move decisively in 2026. Our report tells you where to place those bets and how to reduce execution risk — with the granular segment data and region/application splits available in the full release.
For detailed analysis of this topic, please visit the official page: Car Entertainment System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Waste Treatment Disposal Market—USD 1,328B (2025), 5.98% CAGR to 2032
By pmarketresearch, 2026-07-30
Waste Treatment Disposal Market: Strategic Preview for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking synthesis of our Waste Treatment Disposal Market study — a practical, decision-ready briefing aimed at executives and investors planning material moves in 2026. This preview articulates the macro trajectory, competitive forces, regulatory inflection points, and the strategic choices that will determine who captures value as the market expands. It shows the analytic depth of our work while intentionally omitting granular segment tables so you visit the full study for the actionable spreadsheets, models, and prioritized opportunities.
Waste Treatment Disposal Market
Macro trajectory:Why 2026 is a hinge year
The waste treatment and disposal market has moved from near-term recovery to a durable growth phase. Using 2025 as the base year, our market model traces a five-year historical series (2020–2025) and projects forward across a 2026–2032 forecast horizon. The market recorded consistent expansion through 2025 and — under the central case in our scenario set — is forecast to grow at a compound annual growth rate (CAGR) of 5.98% between 2026 and 2032. In practical terms, the market evolves from an already large base in 2025 to substantially higher aggregate demand by 2032, with sectoral dynamics creating differentiated pockets of margin and capital intensity.
Waste Treatment Disposal Market
That growth profile makes 2026 a decision hinge: near-term capital allocation, M&A timing, and permitting strategies set in motion in 2026 will materially affect the ability to capture market share and returns through the 2030s. Our report quantifies these trade-offs and models investment outcomes under regulatory and demand volatility scenarios so that leadership teams can prioritize with confidence.
Waste Treatment Disposal Market
What the report delivers — operational, not academic
- Proprietary market-sizing and demand-driver model, including scenario runs for high/low growth, energy-price shocks, and accelerated recycling mandates.
- Practical M&A playbook: target screens (asset types, permit portfolios, siloed cash flows), integration risk matrices, and valuation multiples adjusted for regulatory scarcity.
- Capex prioritization framework that links treatment technology choices (landfill, incineration, advanced recycling, RRFs) to unit economics, permitting lead times, and ESG trajectories.
- Regulatory risk & opportunity map: multi-jurisdictional permit timelines, compliance cost forecasts, and public funding overlays (including recycling infrastructure grants and IIJA-related programs).
- Commercial models for long-term offtake and service contracts, including pricing escalation clauses, liability allocation for hazardous streams, and bundling strategies across collection, transport and treatment.
- Operations and digitalization playbook: margin uplift through route optimization, smart-sensor deployment, and asset utilization metrics tied to fleet and facility planning.
- Investor-facing materials: condensed financial models, sensitivity analyses, and scenario-driven IRR projections for greenfield and brownfield investments.
Each deliverable is built to be operational. We do not stop at diagnosis; the study equips teams to execute — from bid/no-bid gate criteria to the first 100‑day integration checklist for an acquisition.
Competitive landscape: consolidation, capability, and regulatory advantage
The market structure is characterized by a broad set of players: global networks, regional operators, hazardous-waste specialists, and niche recyclers. While leading players possess strong brand recognition and scale advantages, concentration levels remain modest relative to other industrial services sectors — a dynamic that sustains both organic competition and deal flow.
- Veolia — Strategic augmentation of U.S. hazardous-waste capabilities through multiple acquisitions and a material agreement to acquire a major U.S. hazardous-waste platform. These moves increase scale in treatment and incineration provision and underscore a playbook focused on permit-rich assets and technical capabilities.
- Waste Management, Inc. — Integration of regulated medical and pharmaceutical waste capabilities into its portfolio strengthens end-to-end solutions and client relationships in healthcare and regulated industries, enabling higher-margin, compliance-driven services.
- Republic Services, Inc. — Continued reinforcement of municipal solid waste and resource recovery integration, where scale in collection complements recycling and energy-recovery options to preserve revenue streams even as disposal volumes fluctuate.
- SUEZ and REMONDIS — European-rooted players leveraging technical water-and-waste competencies and selective U.S. operations to compete on service breadth and technical recycling credentials.
- Clean Harbors , Stericycle (now under a larger corporate umbrella), and Triumvirate Environmental — Specialist providers emphasizing hazardous- and regulated-waste management, with bolt-on acquisitions expanding regional treatment capacity and compliance services.
Recent deal activity — including aggressive hazardous-waste acquisitions and targeted regional buys — signals a near-term wave of consolidation centered on permit portfolios, incineration capacity, and regulated service contracts. These strategic moves create a rising premium for operators who can combine technical treatment capabilities with a defensible permit set and long-term offtake agreements.
Regulatory and infrastructure dynamics shaping 2026 choices
Regulation and public programs are decisive factors in deployment and returns:
- Regulatory capacity signals: the U.S. EPA’s recent assessments confirm that national hazardous-waste treatment and disposal capacity is adequate over multi-decade horizons, but the assessment masks localized constraints — permit bottlenecks, community opposition, and logistical mismatches — that create durable economic rents for operators with the right footprint.
- Permitting and rule updates: ongoing RCRA model-permit updates and select compliance-deadline extensions create both risk (uncertain compliance timelines) and opportunity (first-mover advantage to secure revised, scarce permits).
- Infrastructure funding: federal recycling and waste-infrastructure grant programs accelerate projects across reuse and recycling, which alters feedstock economics for traditional disposal streams and creates new value pools around resource recovery.
Our report maps these regulatory vectors against asset types and provides a decision heatmap indicating where to invest, where to consolidate, and where to steer clear of regulatory drag.
Strategic imperatives for 2026 decision-makers
We distill the market implications into five pragmatic priorities for 2026:
- Prioritize permit-rich acquisitions over volume buys. Given permit scarcity and the long lead time to obtain new authorization, acquiring operating permits and sites with demonstrated community engagement often yields the highest risk‑adjusted returns.
- Segment capex by strategic objective. Allocate growth capital to facilities that improve margins (advanced thermal treatment, energy recovery) and allocate maintenance capital to maximize uptime in hazardous treatment assets where liability and compliance risk are highest.
- Insulate revenues through long-term contracts. Locking in multi-year service agreements with escalation clauses for regulated streams reduces exposure to cyclical swings in municipal volumes and commodity pricing for recyclables.
- Partner for circularity. Invest selectively in partnerships that capture upstream feedstock for resource recovery — this mitigates disposal-only revenue erosion while capturing emerging revenue pools from recovered materials.
- Operationalize regulatory engagement. Build internal capabilities for proactive permitting, community relations, and fast-response compliance teams — these reduce approval timelines and permit-related uncertainty.
Collectively, these actions orient management teams to secure differentiated, permit-anchored positions and to convert regulatory complexity into entry barriers against smaller competitors.
How PW Consulting’s report accelerates execution
Clients use our study in three ways:
- As a transaction workbench — targeted screening lists, valuation stress tests, and post-merger integration playbooks reduce time-to-close and integration risk.
- As an investment-prioritization tool — our capex decision framework translates market growth (CAGR assumptions and scenario ranges) into project-level NPV and payback timelines.
- As a regulatory-playbook — permitting timelines, compliance cost curves, and stakeholder‑engagement templates enable faster approvals and lower political risk premiums.
Closing: why access the full study
This preview demonstrates the analytic scaffolding and strategic prescriptions that inform high‑stakes 2026 choices. We intentionally present the macro sizing, growth trajectory, and competitive dynamics here while withholding the full segment-level tables, regional breakouts, and downloadable financial models. Those detailed layers — including prioritized target lists, downloadable valuation spreadsheets, and segment-specific scenario outputs — are available in the full report and are essential for transaction execution and annual planning cycles.
If your 2026 plan includes capital deployment, M&A activity, or a renewed regulatory strategy, the timing for informed action is immediate. The market’s trajectory — rising from its 2025 base toward a materially larger 2032 size at a 5.98% CAGR — rewards those who align permits, technical capability, and commercial contracts now. PW Consulting’s full Waste Treatment Disposal Market report supplies the playbooks and models to convert that macro growth into measurable value creation.
Contact PW Consulting to access the full study, request tailored scenario runs, or commission a bespoke execution roadmap aligned to your balance sheet and risk appetite.
For detailed analysis of this topic, please visit the official page: Waste Treatment Disposal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hybrid Adhesives & Sealants Market — USD 8,879M in 2025; 6.12% CAGR to 2032
By pmarketresearch, 2026-07-30
Hybrid Adhesives & Hybrid Sealants Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a condensed strategic primer drawn from our forthcoming Hybrid Adhesives & Hybrid Sealants Market study (base year 2025). This brief is designed as a high-value preview for executives who must make decisive 2026 investments — in procurement, R&D, capacity, M&A, and go-to-market — while intentionally withholding the granular segment tables and country-level allocations that make up the full paid report.
Hybrid Adhesives & Hybrid Sealants Market
Market at a Glance: Trajectory and Structural Facts
The hybrid adhesives and sealants market is exhibiting steady, structurally supported expansion. Our market model pegs the global industry at approximately USD 8,879 million in 2025, growing at a compound annual growth rate (CAGR) of 6.12% across the 2026–2032 forecast window. Under the baseline scenario, the market is modeled to cross the USD 13 billion mark by the end of the forecast horizon.
Hybrid Adhesives & Hybrid Sealants Market
This is not a cyclical blip: the historical series from 2020 through 2025 shows recovery and incremental acceleration as applications in construction, transportation electrification, and electronics drive sustained demand. At the same time, market concentration metrics indicate a moderate-to-high consolidation profile with the top three players capturing a meaningful share of demand and the top five controlling well over half of total revenues — an important consideration for competitors and buyers alike when assessing negotiation leverage and innovation partnerships.
Hybrid Adhesives & Hybrid Sealants Market
What’s Driving Growth — and What Could Stall It
- Demand-side vectors: Structural demand is underpinned by building & construction renovation cycles, expanding automotive applications (notably EV battery and lightweight assembly), and increased electronics packaging complexity. Hybrid chemistries are displacing legacy silicones and polyurethanes where formulators can offer multi-performance benefits (adhesion, elasticity, low-VOC emissions).
- Supply-side constraints and raw material volatility: Input-cost dynamics are now a central strategic risk. Recent industry events — including major silicone suppliers announcing double-digit price adjustments and acute silane spot-price pressure linked to photovoltaic feedstock demand and trade barriers — have materially increased production cost uncertainty. Tariffs and supply restrictions (including very high import duties in some markets) exacerbate cost pass-through challenges and inventory management complexity.
- Regulation and sustainability: Low-VOC formulations, greener precursors, and end-of-life considerations are shaping product road maps. Buyers will reward suppliers who can demonstrate lower life-cycle impact without compromising performance.
- Technology substitution and product innovation: The field is evolving beyond simple replacements: hybrid binders and silane-modified polymers are being engineered to meet multi-material bonding demands and faster cycle times, enabling new assembly processes across transport and industrial segments.
Competitive Landscape — Who Matters and Why
The competitive map is populated by consolidated global chemical majors and specialty formulators. Leading incumbents combine broad formulation portfolios with deep channel and OEM relationships; agile regional players compete on price and custom formulation services. Below is a high-level synthesis of strategic positioning among the core players covered in our study:
- Henkel AG & Co. KGaA (Düsseldorf, Germany): Leverages strong brand equity (Loctite, Teroson) and MS-polymer technologies with solutions tailored to automotive assembly and construction. Their R&D emphasis on low-VOC, flexible adhesive systems positions them well for regulatory-driven procurement.
- Sika AG (Baar, Switzerland): A dominant presence in construction and waterproofing with the Sikaflex MS polymer family. Sika’s global distribution and project-level engineering support make them a preferred partner on large infrastructure and commercial builds.
- 3M Company (Saint Paul, US): Differentiates through product-system selling and specialty hybrid adhesive-sealant platforms optimized for UV resistance and industrial bonding. 3M’s technical channels and OEM co-development capabilities are a strategic edge.
- Dow Inc. (Midland, US): Focused play in high-growth segments such as EV battery assembly and industrial bonding, leveraging polymer science to serve electrification trends.
- H.B. Fuller, Bostik (Arkema), Wacker, RPM, and others: These players form a second tier of scale and specialization: hot-melt hybrids, marine-grade formulations, and silane-modified polymers for niche industrial and construction use-cases. Several are accelerating production investments and regional capacity to de-risk supply chains.
Collectively, the market shows active strategic repositioning: production capacity investments, next-gen launches, and targeted product introductions aimed at application-specific performance improvements. Our full report includes competitive scorecards, product pipeline analyses, and supplier risk matrices for these companies.
Recent Developments — Signals You Need to Act On
- Manufacturing scale-up: In mid-2025, a major polymer producer commenced hybrid polymer production at a new European site, signaling renewed upstream investment and potential regional supply rebalancing.
- Next-generation product launches: Late-2025 saw leading adhesive brands introduce MS polymer hybrid solutions tailored for automotive display bonding with improved flexibility and sustainability credentials — a clear indicator that OEM demands for integrated performance and regulatory compliance are accelerating product development cycles.
- Input-price shocks: Since early 2026, notable suppliers have announced significant price increases on silicone inputs after catalyst cost escalations; simultaneously, silane spot markets remain elevated due to competing demand and tariff-driven import constraints. These signals point to an elevated near-term cost base and incentivize buyers to re-evaluate sourcing strategies and hedging frameworks.
Strategic Implications for 2026 Decision Makers
For 2026 corporate planning, the interplay of robust end-market demand and heightened raw-material volatility creates both opportunity and risk. Below are prioritized strategic actions that PW Consulting recommends for market participants, from OEMs and formulators to private equity and distributors.
- Procurement and supply security: Move from spot-centric buying to a hybrid procurement model: longer-term supplier contracts tied to indexed pass-through mechanisms, strategic stockpiles for critical silane and silicone derivatives, and secondary sourcing in lower-tariff jurisdictions. Evaluate supplier performance beyond price — include delivery, formulation fidelity, and sustainability metrics.
- Pricing and margin strategy: Implement value-based pricing for performance-differentiated hybrid solutions (e.g., EV battery adhesives or architectural low-VOC sealants). Use a tiered approach to recover input-cost inflation while protecting volume through contractual escalation clauses and shared-savings clauses for cost reductions.
- R&D and product roadmap: Prioritize chemistries that reduce dependency on tariff-exposed feedstocks and catalysts susceptible to price shocks. Accelerate low-VOC, lower-silane-content formulations, and modularized product platforms that can be rapidly tailored for OEM specifications.
- Capacity investment and localization: Target regional capacity expansions where demand growth is highest and supply-chain friction is most acute. For smaller players, consider toll-manufacturing partnerships with established producers to de-risk capital spend while retaining formulation IP.
- M&A and alliances: The mid-market is ripe for consolidation and capability acquisitions — especially specialist formulators with automotive or electronics credentials. Buyers should prioritize targets with unique formulations, long-term offtake contracts, or localized manufacturing footprints.
- Commercial go-to-market: Differentiate by bundling technical service, application testing, and certification support. Use pilot programs with OEMs to secure specification wins that create switching costs and recurring revenue streams.
What the Full PW Consulting Report Delivers (Operationally Focused)
Our full market study is structured to convert insight into action. Key deliverables include:
- Bottom-up revenue model and scenario forecasts (2026–2032) with sensitivity testing under alternative raw-material and tariff scenarios.
- Competitor scorecards with product portfolios, capacity maps, and strategic positioning assessments.
- Customer segmentation and buying-behavior archetypes for construction, transportation, electronics, and industrial OEMs.
- Detailed supplier risk matrix and procurement playbook (contract templates, indexing approaches, and stock buffer calculus).
- Go-to-market & commercialization playbooks, including value-pricing models and channel optimization recommendations.
- M&A target-screening tool and integration checklists for acquirers.
Note: In keeping with our “teaser-first” approach, this preview intentionally omits the granular segment tables, regional allocations, and per-application revenue tables that substantiate the forecast and inform precise tactical decisions. Those data layers are reserved for subscribers and report purchasers to preserve competitive intelligence value.
Recommended Next Steps for Executives — A 90-Day Roadmap
- Week 1–4: Convene a cross-functional Rapid Response Team (Procurement, R&D, Sales, Finance) to stress-test current supplier contracts and identify critical single-source exposures.
- Week 5–8: Launch RFPs for alternative silane/silicone supply and secure pilot of low-silane formulations with a preferred OEM to validate performance claims and pricing elasticity.
- Week 9–12: Finalize a prioritized investment case (capex vs. toll-manufacturing) and shortlist M&A or partnership targets assisted by our target-screening framework.
Closing — Why 2026 Is a Pivotal Year
The hybrid adhesives and sealants market in 2026 sits at the intersection of accelerating end-market demand and structural supply-chain stress. Companies that move early — securing diversified feedstock access, protecting margin through disciplined pricing, and differentiating via product performance and sustainability — will gain asymmetric advantage. PW Consulting’s full study provides the quantitative foundation and tactical playbooks you need to execute with conviction. For clients ready to convert insight into near-term action, the full dataset and scenario tools unlock the precise levers required to defend margin, capture growth, and evaluate strategic transactions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hybrid Adhesives & Hybrid Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com